

Managing household spending is often misunderstood as a task that requires complicated spreadsheets, lots of numbers, or the ability to track every small expense. In reality, a useful budget must first of all fit each family’s way of life and ability to maintain it. If a plan is overly detailed but is quickly abandoned, it will be less effective than a simple, consistent record-keeping method that accurately reflects the situation.
Creating a budget does not mean cutting every expense or turning daily life into a series of restrictions. The main goal is to help the family understand where its money is going, which expenses should be prioritized, which can be adjusted, and how to prepare for costs that have not yet arisen. When there is a reasonably clear picture of income and spending, financial decisions tend to be less emotional, while family members also find it easier to discuss them with one another.
Start with a realistic picture of cash flow
The first step is to record regular and irregular sources of income over a period long enough to reveal spending habits. For many families, one month is an easy timeframe to use because it corresponds to pay cycles and bill payments. However, if income varies by season, type of work, or contract, looking back over several consecutive months will make the plan more realistic.
When recording income, it is advisable to distinguish between money that is certain to be received and money that may only arise. Fixed salaries, rental income, or stable allowances can be considered separately from overtime pay, commissions, bonuses, or amounts without a clear payment schedule. Uncertain income should not automatically be used to commit to mandatory expenses. If that money does actually come in, the family can put it toward an emergency fund, pay an obligation early, or add it to its savings plan.
On the spending side, an easy way to begin is to divide expenses into a few broad groups instead of trying to create too many small categories. Common groups include housing, food, transportation, education, health care, communications, financial obligations, personal shopping, and entertainment. These groups are not mandatory templates. Families can adjust them to reflect their own circumstances, as long as the classification helps everyone understand and use it.
Distinguish between fixed, variable, and irregular expenses
Not every expense can be handled in the same way. Fixed expenses generally have relatively stable amounts and payment dates, such as rent, contract-based service fees, or certain recurring payments. Variable expenses change according to usage, such as electricity, food, transportation, or shopping. Irregular expenses, meanwhile, may not occur every month but still need to be taken into account, such as repairing household items, gifts and contributions for family occasions, term-based tuition, or a planned trip.
This classification helps avoid a common mistake: assuming that if an expense does not occur in a given month, it does not need a place in the plan. An expense that appears only a few times a year can still create pressure if the family is completely unprepared when it becomes due. For predictable expenses, it is advisable to estimate the total amount needed over a year and then divide it into smaller portions to prepare gradually. This approach does not require perfectly accurate predictions, but it creates greater preparedness than waiting until payment is due and then scrambling to find the money.
For variable expenses, it is not necessary to set a rigid figure from the outset. The family can track them for a few weeks or months and then determine a reasonable spending range. For example, instead of requiring the food budget to be identical every month, the family can set a reference amount and allow adjustments when there are guests, an unusual work schedule, or changes in daily routines.
Set priorities instead of focusing only on cutting costs
A sustainable budget should not only answer the question “What should be cut?” but also “What should the money be used for first?” Expenses related to housing, basic food, health, education, necessary transportation, and committed obligations are generally considered before discretionary purchases. The family can then allocate what remains to emergency funds, long-term goals, and activities that contribute to quality of life.
In practice, the boundary between needs and wants is not always absolute. An expense may be unnecessary for one person but meaningful to another. Therefore, rather than imposing a common list, family members should discuss the reason for each expense. Eliminating an expense with significant emotional value but little effect on the budget can sometimes make the plan feel burdensome and difficult to maintain. Conversely, small expenses that recur frequently may deserve review if they no longer fit current habits.
The budget can be divided into three priority layers. The first layer consists of expenses that must be paid to maintain daily life and fulfill obligations. The second consists of goals that require preparation, such as an emergency fund, education, repairs, or plans for major purchases. The third consists of flexible expenses that can increase or decrease depending on the circumstances. This division helps the family make decisions more quickly when income changes or an unexpected expense arises.
Create a reserve that matches your means
An emergency reserve is often overlooked when all income has already been allocated to immediate expenses. However, there is no need to wait until a large sum is available before starting. Even a small amount set aside regularly can build a habit and reduce pressure when an unexpected situation arises.
The reserve should be kept separate from everyday spending money to prevent it from being used accidentally. The family can assign a clear purpose to each portion, such as one portion for household emergencies, one for medical or repair costs, and one for long-term goals. If financial capacity is limited, prioritizing a small but regular reserve may be more realistic than setting an overly ambitious target and quickly giving up.
Preparation is not limited to cash. Knowing exactly where important documents, contracts, due dates, and necessary contact information are kept will help the family handle situations more smoothly. A good financial plan should therefore be accompanied by a clear way of storing information, without turning it into a complicated system that is difficult for users to access.
Choose a record-keeping method the whole family can maintain
There are many ways to track a budget: a paper notebook, a spreadsheet, a phone app, or a simple summary table. No tool is automatically suitable for everyone. The most important criteria are that users can update it regularly, review it easily, and understand what the numbers represent.
If the family has few transactions or prefers handwritten records, a notebook with columns for the date, description, spending category, and amount may be enough. If there are many payments, a spreadsheet makes it easier to calculate totals and compare different months. An app may suit people who frequently use their phones, but attention should be paid to protecting accounts and personal information. Regardless of the method, unnecessary sensitive information should not be entered, and access should not be shared indiscriminately.
Record-keeping does not necessarily have to take place immediately after every transaction if doing so is tiring. The family can choose a fixed time each day or week to update the records. What matters is not leaving gaps so long that small expenses are forgotten and end-of-period figures become inaccurate. When an expense cannot be remembered, it is better to mark it for later verification than to make an overly arbitrary estimate.
Review the budget and adjust it when circumstances change
A budget is not an immutable commitment. Income, work, prices, health, and family needs can all change. Therefore, it is advisable to hold a short review at the end of each month or after a set period. The purpose of the review is not to find someone at fault, but to identify aspects of the plan that do not fit well.
You can begin with three questions: Which expenses were higher than expected? Which were lower than expected? What caused the difference? If food costs increased because the work schedule changed, the solution may be to adjust shopping habits or the budget amount, rather than simply concluding that the family lacked spending discipline. If a recurring subscription is no longer being used, checking and canceling it properly may be more effective than cutting back on essential needs.
When income decreases, the family should prioritize securing obligations and basic living expenses while temporarily postponing nonessential spending. When income increases, it is not necessary to raise all spending levels immediately. Some of the additional money can go toward an emergency reserve, long-term goals, or existing obligations. Small but deliberate adjustments are often easier to maintain than overly drastic changes.
Turn the budget into a family conversation
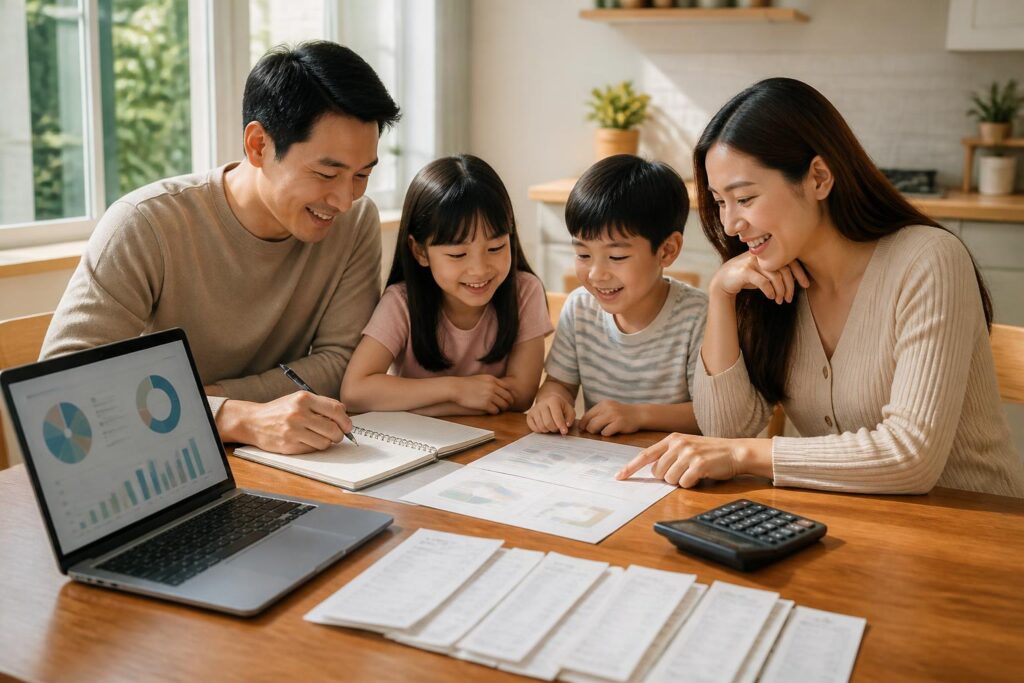
A budget will be difficult to implement if only one person knows all the information while the others do not understand the shared limits. In families with multiple members, it is advisable to agree on basic principles, such as which expenses need to be discussed in advance, which each person can decide on independently, and how to handle a large unexpected expense. Children can also be taught at an age-appropriate level, such as learning to distinguish needs from wants or helping track a simple savings goal.
Discussions about money should focus on plans and solutions rather than turning into blame. Each person has different spending habits, so transparency should be accompanied by respect. When all family members understand the shared goals and know that the budget is designed to support daily life rather than control one another, cooperation will come more naturally.
An effective family budget does not need to be perfect from the first attempt. It is enough to begin by recording cash flow, categorizing expenses, identifying priorities, and setting aside part of the money for uncertainties. After each review, the plan can be adjusted to better reflect real life. The greatest value of a budget does not lie in ensuring that every figure is always perfectly accurate, but in its ability to help the family stay prepared, communicate clearly, and make decisions that fit its resources.
